
October 9, 2026/
The persuaders: Asia CEOs make their case to HQ October 9, 2026 What’s changing? As geopolitical shocks and economic uncertainty compete for attention,...
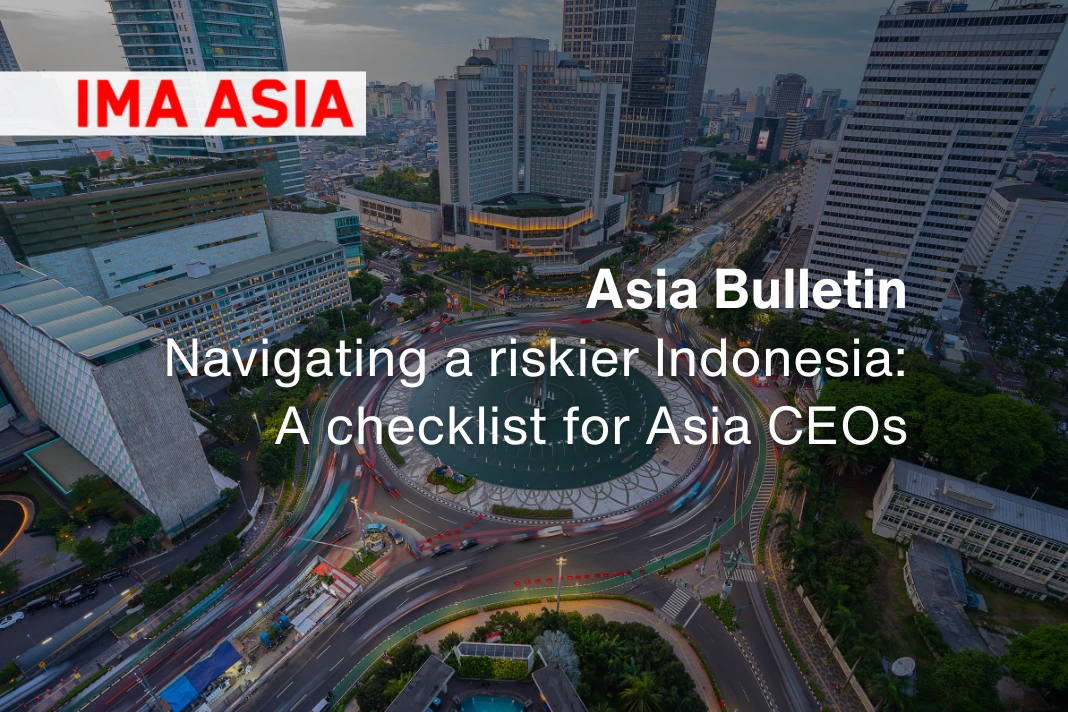
Global capital gatekeepers have been raising the alarm — in ways not seen for decades — warning that the economy is heading into fiscally dangerous waters.
Fitch and Moody’s have put negative warnings on their ratings. And MSCI said that unless the stock market is cleaned up they’d remove Indonesia from the emerging markets index. So, three big warnings. In 25 years of covering Indonesia — not since the 1997 Asia Financial Crisis — have I seen such serious warnings handed out to this country.
As a result, Indonesia’s growth rate targets have been recalibrated downwards. In April, the World Bank also lowered its rate from 4.8% to 4.7%.
Recently, IMA Asia nearly halved its initial growth forecast for 2026.
Indonesia is caught between poor domestic policy settings by President Prabowo’s government, which undermine growth and reduce resilience, and a surge in energy costs, which will hurt consumers. Our GDP forecast drops to 2.6% growth in 2026 (prior 4.6%) and 3.5% in 2027 (prior 4.4%).
The gap between these two reflects, in part, a disagreement about how much damage domestic policy choices and the external energy shock will inflict.
Here is how one policy expert sees it.
2026 is the first year in which the budget is fully Prabowo’s rather than inherited from the former president, Jokowi (Joko Widodo). This year will reveal whether political ambitions can be financed without undermining fiscal credibility. There are three tests to watch.
First, whether the government can fund its expensive flagship programs while debt service and spending are already high. Second, whether market confidence can be preserved amid concerns over policy predictability. And third, can the external shocks, such as inflation from the war, be managed without turning fiscal strain into a governance problem?
Indonesia’s US$1.47 trillion economy is hard to ignore; it accounts for nearly 40% of ASEAN’s economy.
Foreign firms will need to align their value propositions with increasingly nationalistic priorities to capture the most upside.
Indonesia’s model is shifting. The question is not how fast Indonesia can grow, but what kind of growth is being built and who benefits from it. The fiscal constraints, declining middle class and state-directed policy are signals that the economy is rebalancing its trajectory, which creates both opportunity and uncertainty.
Reality check: Political imperatives have become more important than balanced budgets. A full policy about-face or a return to the way things were is unlikely.
There is limited room for a full reversal. Prabowo’s flagship programs are politically central to his presidency. Prabowo associates himself with his social programmes, especially the free nutritious school meal. Scaling them back sharply would carry a high cost.
Yet, the government has shown a willingness to heed warnings. They made course corrections with the stock market, after all.
The more realistic scenario is adjustment at the margins, such as improving communications to boost market confidence. The authorities moved on capital market reforms following the MSCI warning, including new measures to improve ownership transparency. There are opportunities, but uncertainty around execution and policy consistency will persist.
Zoom out: Many Asia CEOs have experience with a similar state-first market — China — and can bring that to bear. Opportunities exist for firms attuned to the government’s priorities.
Indonesia will reward firms that align with its direction in industrial development, job creation, and long-term capability building. Indonesia will continue to grow, albeit slowly. The quality, inclusiveness, and sustainability of that growth will depend on how well the government manages the trade-offs it is now facing. This is the story to watch in 2026.
An endorsement: An Asia CEO at an Australian firm, with a long history in Indonesia, remains optimistic about their business even as infrastructure projects are delayed.
The market is very good in Indonesia, and we are very positive about our prospects. It is not so much the infrastructure spend, which has dropped off, but what follows it. The enablement of economic activity is important to us. Our products are driven by the construction market for industrial and commercial buildings. We see very strong prospects for this market in local business growth. We are improving relations with our suppliers and customers.
Get in line: Contributing to economic growth is no longer sufficient to stay in the government’s good graces. Foreign firms are expected to contribute to nation-building objectives. Raw commodity exports are increasingly discouraged in favour of downstream processing.
The government views industrial policy as a tool for national upgrading. Not just export growth. Prabowo has repeatedly mentioned ‘down-streaming’. Indonesia should no longer export raw materials if it can process them domestically to capture more value, create more jobs, and gain greater strategic leverage. Firms aligned with state priorities on local processing in strategic sectors will benefit.
For example, copper, bauxite, and nickel are the most commonly cited examples in Prabowo’s downstream push
Partners wanted: Foreign firms should seek to become value-added partners, especially if they can bring advanced financial and management approaches that Indonesian companies lack.
The implication for foreign investors is clear. Success in Indonesia’s infrastructure sector depends less on being a contractor and more on being a strategic partner able to share risk and connect infrastructure to broader economic outcomes.
Constructing tangible infrastructure is no longer the priority…
Pak Jokowi’s administration created a substantial asset base. So, the current focus is on completing, operationalising, and connecting these assets to real economic activity. Pak Prabowo doesn’t aim to build new infrastructure.
… the task is to unlock the intangible value of existing infrastructure.
The government is not just looking for capital; they want partners who can help make infrastructure work financially, operationally, and economically.
Go deeper: Indonesia welcomes foreign partners that…
structure viable financing models like blended finance, PPP schemes, or long-term capital to reduce pressure on the state budget
bring operational expertise to improve asset performance. For example, improve port efficiency or build more reliable power systems.
link assets to economic value by supporting downstream industries, logistical efficiency and regional development. For example, projects that are integrated with industrial zones, supply chains, or export capacity are preferred over standalone assets.
align with strategic priorities, including energy transition, digitalisation, or connectivity beyond Java, that reflect a broader shift towards infrastructure as industrial policy rather than public works.
Foreign firms conducting outreach can expect their views to be heard by government decision-makers in Indonesia. It is advised to start discussions early in the policymaking process to have the most impact.
I have always found Indonesian ministers and the government leaders to be immensely open to discussion. They are very keen to hear from outsiders and will make a course correction if needed. The earlier the views are expressed, the better.
Officials will be more frank about the challenges they are facing when discussions are held behind closed doors.
Many in the cabinet are aware of the conflicting policy priorities and will share honest and clear insights from the government perspective. But just don’t ask them to do so on a public stage, they prefer closed room meetings in a safe space.
Below are three potential problem areas that could derail Indonesia’s progress.
Political priorities are coming up against the hard reality of Indonesia’s fiscal framework, deepening divisive centre-local tensions.
The central government has kept to the 3% legal threshold for new debt relative to GDP, but it is financing its projects in controversial ways, such as by withholding funds typically earmarked for regional transfers.
The government remains committed to financing its flagship programs, which is creating a significant fiscal and political problem. Roughly speaking, one-third of the central budget is used to service interest on loans and debt. One-third is for central government operations, and the remaining third is for regional transfers to the provinces. These proportions cannot be maintained if the flagship programs continue. In March, it was announced that the deficit already exceeded 240 trillion rupiah, and the regional transfers were cut from 25-30% down to 17%.
Cash-strapped regional governments have responded to the revenue shortfall by raising taxes or implementing austerity measures. Local backlash and uprisings have resulted.
Resistance movements are already showing up in central Java, north Sumatra, west Kalimantan, north Sulawesi and Nusa Tenggara. It should be clear: reducing local transfers is a major budget change and a giant political move. This is having a big impact to dampen demand in the market.
President Prabowo has the largest cabinet in recent Indonesian history, with 48 ministries and 112 ministers and vice-ministers. This has had the unexpected result of consolidating power in fewer hands at the top.
A large cabinet can present a wider coalition and broaden political inclusion. But it also increases coordination costs and overlapping mandates. This is a paradox. The cabinet looks strong, but decision-making becomes centralised because only the president can reconcile the competing interests inside it. Policy becomes more dependent on presidential arbitration than on streamlined institutional processes.
The rule of law and regulations may take a back seat to presidential priorities. For the Asia CEO and those at HQ, the Indonesian operating environment will become harder to evaluate from the outside, more opaque, and will require more trust in the local team.
Policy outcomes become more personality-driven. Businesses increasingly need to understand presidential priorities, not just formal regulations.There is a shift away from technocratic dominance toward more politically aligned economic management.
The new minister of finance, responsible for many of the nation-building projects, is particularly powerful and a strong supporter of big industry and results that scale. Concentrated cash flows increase financial risks.
Pak Prabowo looks at Pak Purbaya as one of the most technically capable figures in the cabinet. Prabowo see him as intellectually strong, analytical, and more grounded. But his approach is more heterodox, interventionist, and less anchored in conventional fiscal orthodoxy than his predecessor.
Working on government initiatives means adapting to abrupt policy shifts.
Engagement with Indonesia’s economic policy may become more strategic and state-mediated. Opportunities are significant, especially in large-scale state-backed initiatives, but they also entail higher governance and policy risks. Purbaya is a driver of a more interventionist economic model. Success will depend less on vision and more on the institutional discipline and execution.
Consumer brands are worried about the decline of the middle class. The Asia CEO of an affordable premium brand remains optimistic about the size of the Indonesian market, yet is concerned that fewer people will be able to afford their products.
Indonesia faces a challenging situation with a shrinking middle class from 21.5% of the population in 2019 to 17.1% in 2024. This group accounts for 81% of household spending and is the main engine of consumption. A weaker middle class means softer discretionary spending and lower growth. It also means lower productivity.
It also appears the new government has not made growing the middle class a direct priority. The middle class is not the organising principle of policy as it could be.
Indonesia cannot expand its middle class by redistribution alone and not by growth alone either — it should expand the middle class by creating a large number of productive, formal, upwardly mobile jobs and by investing in high-quality education. But there is no clear government agenda to support this yet.
A strong middle class is necessary for more than just consumption; it sustains economic growth and national advancement overall. There is still time to address this policy oversight.
If Prabowo can align his industrial policy, human capital investment, and urban affordability around growing the middle class, the trajectory can improve. If the middle class remains too thin to sustain growth, all other gains might get hollowed out.
Interested in joining the discussions?
Contact us to learn more.
The persuaders: Asia CEOs make their case to HQ October 9, 2026 What’s changing? As geopolitical shocks and economic uncertainty compete for attention,...
Currency hedging & Inflation predictions September 17, 2026 What’s changed: Asia CEOs and managers discussed how they are managing a...
Asia market roundup: stability, growth, and the cost of complexity September 16, 2026 What’s new? As political and economic realities...